
 Firefighter Simulator Training Services Market | 2026-2036
Firefighter Simulator Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
Firefighter Simulator Training Services Market Foresight
Municipal fire departments are redrawing procurement priorities away from legacy live-fire drills toward repeatable simulator-based curricula. LION Protects anchors its position through captive production of protective gear paired with training content. KONGSBERG dominates maritime and industrial fire simulation with systems that replicate confined-space emergencies. Dräger leverages its respiratory equipment installed base to cross-sell scenario-based training modules.
Firefighter simulator training services deliver controlled-environment skill replication through immersive digital environments, thermal feedback systems, and physiological monitoring interfaces that replicate smoke visibility, heat stress, and decision fatigue without combustion hazards. The service architecture spans in-person training, virtual reality training, hybrid training, and on-demand training; virtual reality training commands the fastest expansion as hardware costs fall and headset fidelity improves. Instructor-led delivery still occupies the largest revenue pool within delivery models, though blended learning is displacing pure classroom formats as departments seek scheduling flexibility.
NFPA standards, OSHA training mandates, and FAA firefighting certification requirements shape product specifications and create compliance-driven demand across North American buyer segments. The EU's MDR and CE marking frameworks govern simulator hardware imports into European training academies, while China's GB standards and MIIT technology certifications structure market access for foreign VR training platforms. Stakeholders must track how regulatory divergence between jurisdictions fragments content localization requirements and whether hybrid training architectures satisfy multiple certification bodies simultaneously.
Market Dynamics
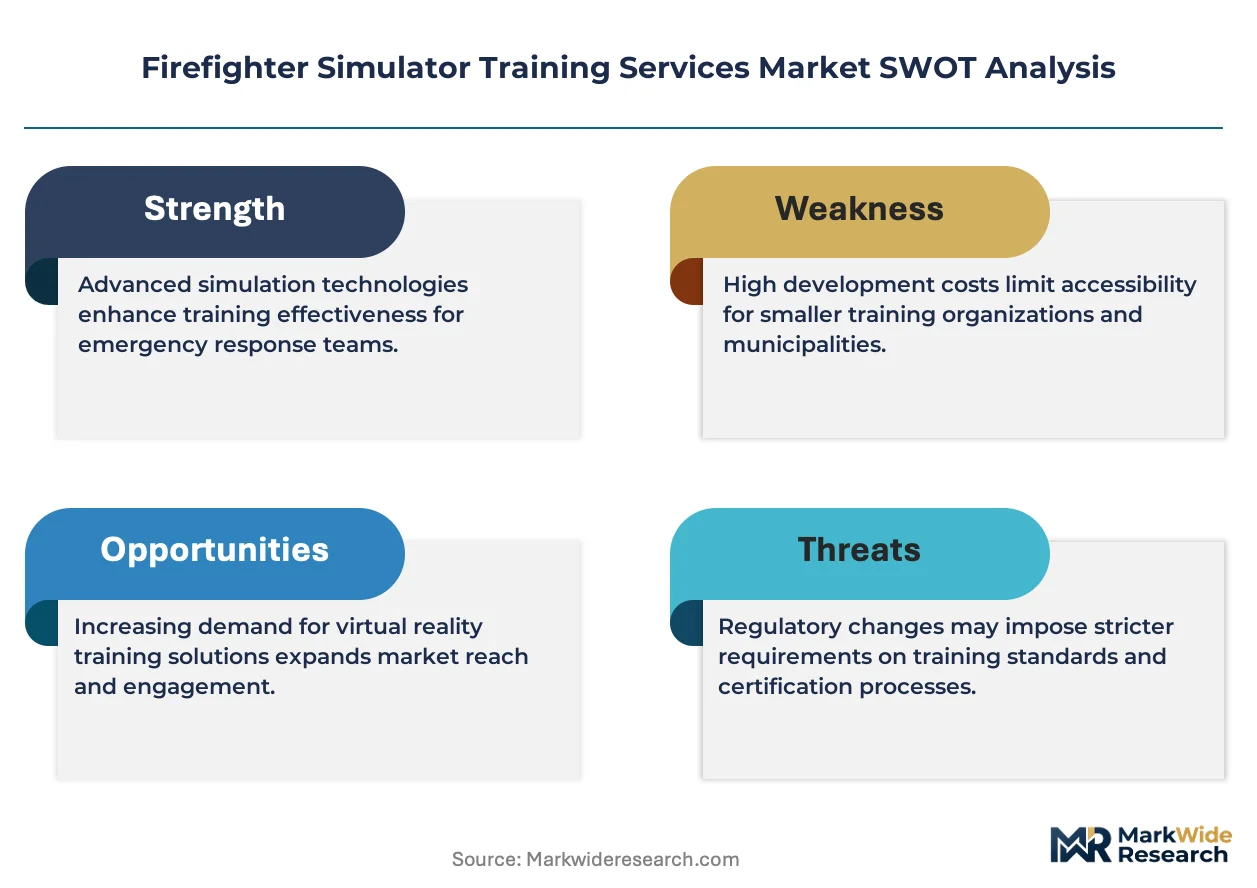
Municipal fire departments face intensifying pressure from OSHA and NFPA standards that restrict live-burn training hours while mandating repeatable skill verification. This regulatory compression is redirecting capital toward simulator-based certification architectures that eliminate combustion hazards without sacrificing scenario complexity.
Growth Catalysts
- NFPA 1403 Live-Fire Restrictions:Tightened safety protocols in the United States are forcing departments to replace burn-room exercises with thermal-feedback simulators that replicate heat stress without structural fire risks.
- Virtual Reality Hardware Cost Collapse:Headset price erosion below $500 per unit is enabling small and mid-sized fire districts to deploy immersive training previously limited to major metropolitan budgets.
- Maritime Safety Mandates:International Maritime Organization protocols for confined-space emergency response are driving port authorities and shipping operators toward digital simulation for crew certification.
Market Restraints
- GPU Supply Concentration:Taiwan-based semiconductor fabrication bottlenecks are inflating rendering hardware costs for high-fidelity smoke and flame visualization engines.
- Content Localization Burden:Divergent certification requirements between OSHA, EU MDR frameworks, and China's GB standards force training providers to maintain parallel scenario libraries.
- Physiological Feedback Hardware Costs:Biometric monitoring vests and thermal haptic suits remain prohibitively expensive for volunteer fire companies comprising 65 percent of US departments.
Strategic Opportunities
- Industrial Facility Underpenetration:Petrochemical and data center fire brigades in India and Brazil lack structured simulator programs, creating first-mover openings for scenario-as-a-service platforms.
- AI-Generated Scenario Variation:Large language models trained on incident reports can auto-generate unlimited training permutations, reducing content production cycles from months to hours.
- Federal Procurement Channel Expansion:US Department of Homeland Security grants specifically earmark simulator acquisition, bypassing municipal budget approval friction.
Industry Challenges
- Instructor Certification Pipeline Collapse:Experienced firefighters capable of translating field expertise into simulator curriculum design are retiring faster than training programs can replace them.
- Legacy SCBA Integration Friction:Departments demand simulator compatibility with existing Dräger and MSA respiratory equipment, forcing hardware vendors to engineer backward-compatible sensor interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firefighter Simulator Training Services Market |
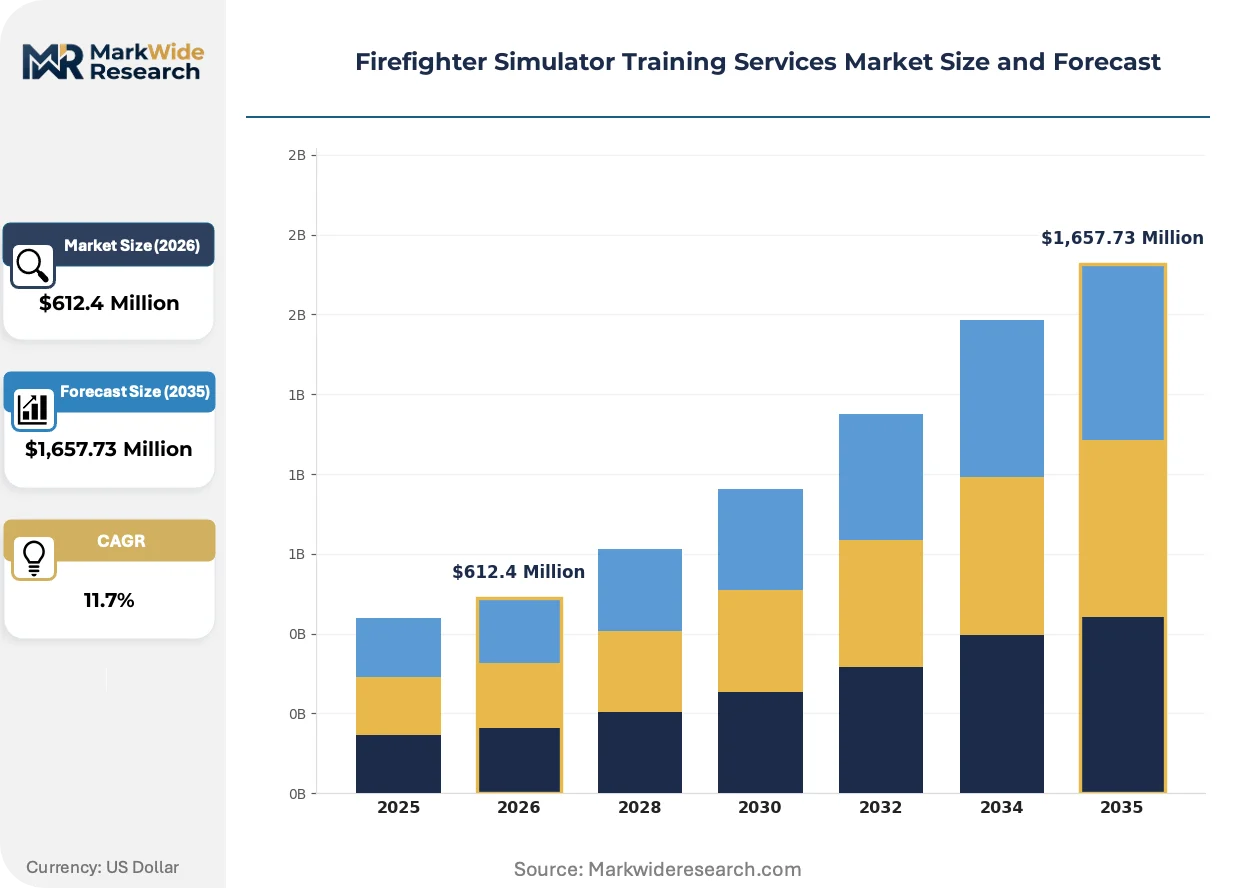
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,657.73 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Person Training, Virtual Reality Training, Hybrid Training, On-Demand Training Delivery Model: Instructor-Led, Self-Paced, Blended Learning, Online Workshops End User: Fire Departments, Training Academies, Private Organizations, Government Agencies Technology: Immersive Simulators, Augmented Reality, 3D Modeling, Scenario-Based Training |
| Companies Covered | FAAC Incorporated, LION Protects, KONGSBERG, ECA Group, Conair Aerial Firefighting, Arotech, Intellic Technologies, Interfire Products Oy, Dräger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firefighter Simulator Training Services Market Shifts & Advancements
Immersive training architectures are fragmenting into specialized modalities that match scenario fidelity to specific skill domains rather than pursuing universal simulation platforms. This specialization is compressing procurement cycles and enabling modular system expansion.
Portable thermal-feedback units are miniaturizing from room-scale installations to wearable vest arrays that replicate heat gradients through localized warming elements. Rural fire districts in Australia and Canada are adopting these mobile systems for regional training rotations. The technology is miniaturizing capital requirements from six-figure fixed installations to sub-$10,000 deployable kits.
EU MDR certification requirements for medical-grade physiological monitoring devices are spilling into firefighter training equipment classification. Simulator vendors must now document biocompatibility and electromagnetic safety for chest-worn sensor arrays. German and French training academies are delaying procurement until CE marking pathways clarify, compressing near-term demand in Western Europe.
Subscription-based scenario libraries are displacing perpetual-license software sales as the dominant commercial model. Fire departments in California and Texas prefer monthly access to expanding content catalogs over single-purchase scenario packages. This shift concentrates recurring revenue with platform operators while reducing upfront capital barriers for budget-constrained agencies.
Firefighter Simulator Training Services Market Segmentation
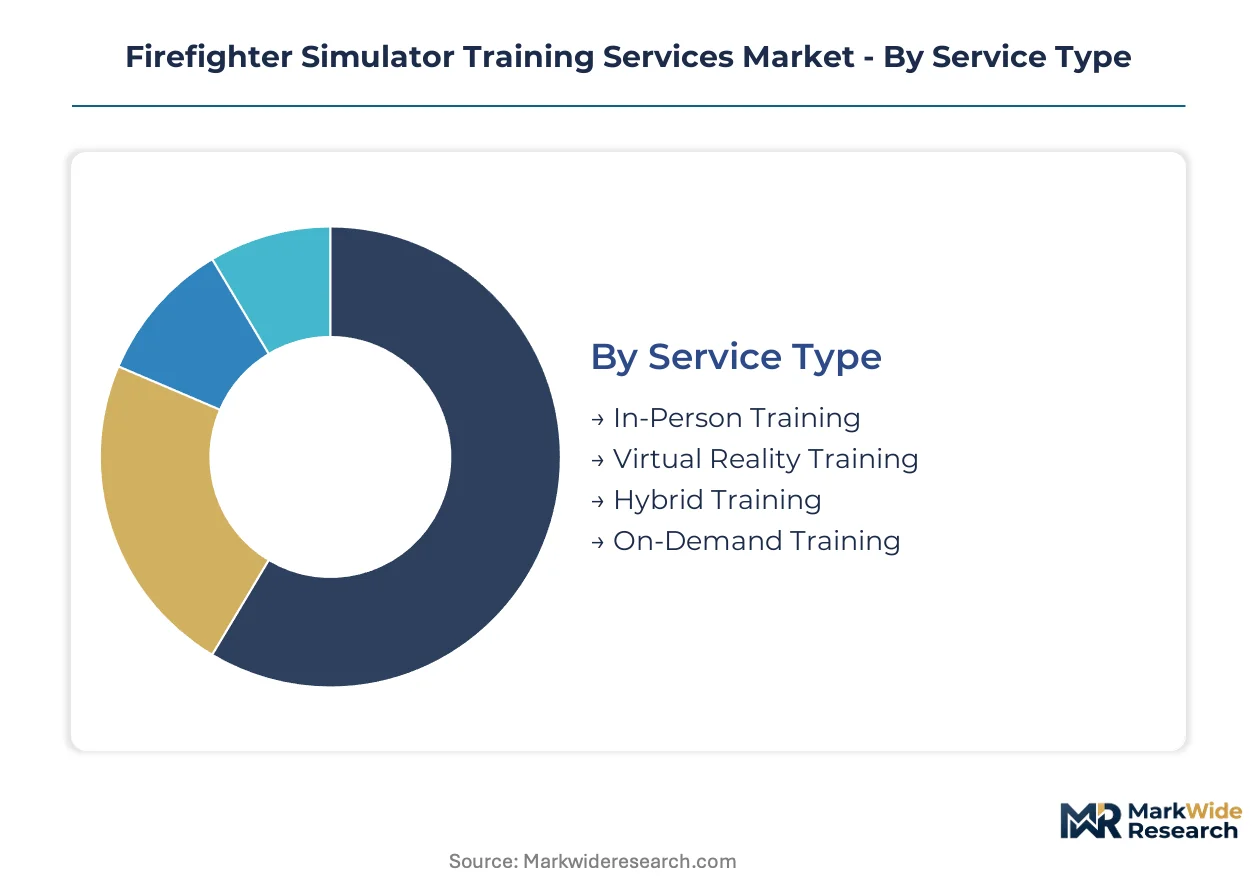
Firefighter simulator training services fragment across service architecture, instructional modality, and technology platform. Procurement patterns diverge sharply between municipal departments seeking compliance certification and industrial brigades demanding scenario customization.
Service Type:
Domestic procurement concentrates in instructor-dependent formats, while export-led growth flows through scalable digital platforms. North American departments favor thermal-feedback installations, whereas Asian markets prioritize portable VR deployments.
- Virtual Reality Training:Headset-based immersion replicates smoke obscuration, heat stress, and structural collapse through spatial audio and haptic feedback. Demand clusters in United States municipal departments replacing restricted live-burn exercises under NFPA 1403. Federal procurement channels accelerate adoption through Department of Homeland Security grant earmarks.
- Hybrid Training:Combines physical props with digital overlay, enabling SCBA compatibility testing alongside scenario decision trees. German and French academies favor this architecture for CE marking compliance with EU MDR biocompatibility requirements for physiological monitoring.
- In-Person Training:Instructor-facilitated sessions using fixed thermal-feedback installations.
- On-Demand Training:Cloud-accessible scenario libraries supporting asynchronous skill verification.
Instructor-Led commands the established base. The steepest expansion runs through Virtual Reality Training.
Delivery Model:
Cost tiering separates enterprise-grade installations from subscription-based content access. Premium deployments integrate biometric monitoring; economy tiers rely on software-only immersion.
- Instructor-Led:Facilitator-directed sessions in dedicated simulation facilities with multi-student thermal environments and real-time physiological tracking. United States metropolitan departments dominate procurement, driven by OSHA mandate compliance and NFPA certification renewal cycles.
- Blended Learning:Rotates classroom instruction with simulator modules, reducing facility occupancy costs. Canadian and Australian rural districts adopt this format for regional training rotations across dispersed volunteer companies.
- Self-Paced:Individual progression through standardized scenario libraries without facilitator oversight.
- Online Workshops:Synchronous virtual instruction for theoretical and procedural knowledge transfer.
Instructor-Led retains revenue concentration. Blended Learning is climbing the fastest as scheduling flexibility becomes decisive in procurement evaluation.
End User:
Application intensity varies by regulatory exposure and incident frequency. High-hazard industries demand scenario customization; public agencies prioritize certification throughput.
- Fire Departments:Municipal and county agencies conducting recruit certification and annual skill recertification. United States departments comprise the dominant demand pool, with NFPA 1403 restrictions eliminating live-burn alternatives. Budget fragmentation between career and volunteer companies creates tiered procurement patterns.
- Private Organizations:Petrochemical, data center, and manufacturing fire brigades requiring facility-specific scenario development. Brazil and India present underpenetrated expansion opportunities as industrial safety mandates tighten.
- Training Academies:Centralized instruction facilities serving multiple department contracts.
- Government Agencies:Federal and state-level emergency management and military firefighting units.
Fire Departments anchor volume demand. Private Organizations present the steepest expansion trajectory as industrial facility mandates proliferate.
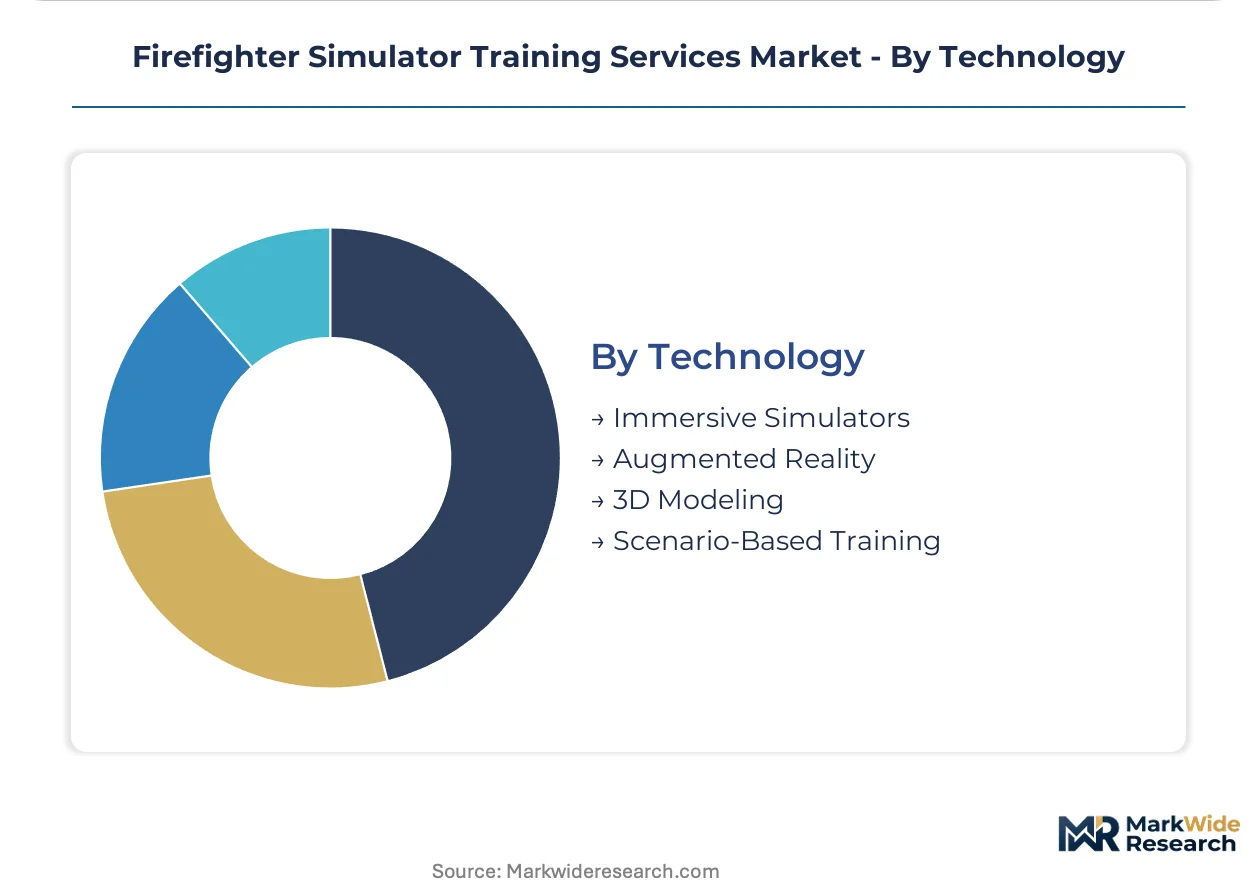
Technology:
Supply concentration in GPU fabrication and sensor manufacturing shapes platform availability. High-fidelity rendering depends on Taiwan-based semiconductor supply chains.
- Immersive Simulators:Room-scale installations combining thermal feedback, smoke generation, and structural collapse simulation. Maritime and industrial applications concentrate demand through KONGSBERG's confined-space emergency systems. IMO safety protocols for crew certification sustain replacement cycles.
- Scenario-Based Training:Modular software platforms enabling rapid content customization for facility-specific hazards. Subscription revenue models displace perpetual licenses in California and Texas procurement, concentrating recurring revenue with platform operators.
- Augmented Reality:Overlay visualization on physical training environments through transparent displays.
- 3D Modeling:Pre-visualization and architectural planning for training facility design.
Immersive Simulators retain installed-base dominance. Scenario-Based Training gains share fastest through AI-generated content variation reducing production cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's industrial firefighting infrastructure anchors European demand for maritime simulation systems, while the Trans-Alaska Pipeline System underwrites North American investment in cold-weather emergency response training platforms.
United States
Department of Homeland Security grants earmark simulator acquisition for municipal departments replacing restricted live-burn exercises. OSHA and NFPA 1403 standards compress training alternatives toward thermal-feedback installations. Houston's petrochemical corridor drives demand for facility-specific scenario development among industrial fire brigades.
Germany
EU MDR certification requirements for biocompatibility and electromagnetic safety delay procurement of chest-worn physiological monitoring arrays. CE marking pathways for medical-grade training equipment remain unresolved. Hamburg's maritime training academies sustain replacement cycles for KONGSBERG's confined-space emergency systems under IMO protocols.
China
GB standards and MIIT technology certifications structure market access for foreign VR training platforms. Dual carbon goals accelerate replacement of combustion-based training with zero-emission simulation alternatives. Shanghai's port authorities deploy digital crew certification systems for international shipping compliance.
Australia
Rural fire districts adopt portable thermal-feedback vest arrays for regional training rotations across dispersed volunteer companies. TGA-equivalent safety frameworks govern equipment import approvals. Queensland's mining belt generates concentrated demand for confined-space emergency simulation.
Brazil
Industrial safety mandates tighten for petrochemical and data center fire brigades lacking structured simulator programs. ANVISA-equivalent equipment certification creates compliance barriers for foreign platform entry. São Paulo's manufacturing corridor presents first-mover openings for scenario-as-a-service platforms.
Firefighter Simulator Training Services Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and content localization capabilities. The vendor base splits between integrated protective equipment manufacturers and pure-play simulation platform operators. Three archetypes dominate: gear-integrated training providers, maritime-industrial simulation specialists, and subscription-based scenario library operators. Consolidation pressure runs through backward integration into sensor hardware and geographic expansion via distributor networks.
Within the gear-integrated tier, LION Protects and Dräger exemplify archetypes that pair captive protective equipment production with training content cross-sell. KONGSBERG occupies a distinct position among maritime-industrial specialists, replicating confined-space emergencies for port authorities and shipping operators. These three anchors illustrate how installed-base leverage in adjacent equipment categories shapes competitive positioning in training services.
| Leading Market Players |
|---|
| FAAC Incorporated |
| LION Protects |
| KONGSBERG |
| ECA Group |
| Conair Aerial Firefighting |
| Arotech |
| Intellic Technologies |
| Interfire Products Oy |
| Dräger |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with Taiwan-based GPU foundries lock in rendering hardware access and stabilize input costs for immersive simulator manufacturers serving NFPA-compliant municipal departments. These contractual structures insulate premium-tier vendors from spot-market volatility while forcing economy-tier competitors toward shorter procurement cycles.
Pricing Analysis
Volume-discount tiering separates enterprise installations above fifty seats from mid-tier departmental deployments and single-unit volunteer company purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked physiological monitoring arrays commanding substantial premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because headset price erosion below five hundred dollars eliminates hardware margin buffers. Volunteer fire companies comprising sixty-five percent of United States departments exhibit acute price sensitivity, whereas metropolitan departments prioritize certification throughput over unit economics.
Supply Chain Analysis
Strategic stockpiling of thermal-feedback sensor arrays and haptic vest components dominates inventory strategy among established simulator vendors anticipating Taiwan semiconductor fabrication bottlenecks. GPU supply concentrates in Taiwan, South Korea, and the United States, while biometric sensor manufacturing rests on Chinese and German component ecosystems. Raw material dependencies span gallium nitride for thermal emitters, lithium-polymer cells for portable units, and specialized polymers for haptic suit construction. Single-source vulnerability in Taiwan-based rendering chip fabrication threatens production continuity for high-fidelity smoke visualization engines. Distribution runs through direct municipal procurement channels, federal grant administrators, and specialized emergency services distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's expansion trajectory hinges on a widening gap between retiring field instructors capable of curriculum design and the digital-native technologists needed to operationalize AI-generated scenario platforms. This capability asymmetry will determine competitive viability across the forecast window.
For Market Incumbents: Secure exclusive content partnerships with municipal training academies before subscription-based scenario libraries commoditize proprietary curricula. Backward integration into physiological monitoring hardware manufacturing defends margin position against pure-play software entrants exploiting open-source rendering engines. Lock in SCBA compatibility certifications with Dräger and MSA to erect switching costs around installed respiratory equipment bases. For New Entrants and Emerging Players: Scenario-as-a-service gaps in Brazil and Indian industrial fire brigades offer beachhead positions where incumbent geographic coverage remains thin. Petrochemical facility mandates in São Paulo's manufacturing corridor present the most penetrable entry point. Lead with AI-generated scenario variation capabilities that compress content production cycles from months to hours, bypassing the instructor certification pipeline collapse that constrains established competitors. For Investors and Strategic Acquirers: Capital is best deployed toward subscription-platform operators with demonstrated recurring revenue traction and modular content architectures capable of cross-border localization. Long-term viability favors vendors whose revenue concentration shifts from perpetual-license hardware sales toward expanding scenario library access. Watch for NFPA 1403 restriction tightening as the inflection signal that accelerates municipal procurement away from live-burn alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Generated Scenario Development | Compresses content production cycles and enables unlimited training permutations for municipal certification programs. |
| Backward Integration into Sensor Hardware | Captures margin from biometric monitoring vests and thermal haptic suits demanded by OSHA-compliant departments. |
| Subscription Platform Migration | Concentrates recurring revenue with operators while reducing upfront capital barriers for budget-constrained volunteer companies. |
| Federal Procurement Channel Expansion | Bypasses municipal budget approval friction through Department of Homeland Security grant earmarks for simulator acquisition. |
| CE Marking Compliance Investment | Unlocks German and French academy demand stalled by unresolved EU MDR certification pathways for medical-grade training equipment. |
Research Methodology
A spread of perspectives from fire training academy directors, municipal procurement officers, SCBA equipment product managers, and federal grant administrators converged on the working assumptions underlying demand projections. Primary fieldwork with simulator platform engineers and physiological monitoring device manufacturers combined with secondary validation through NFPA standards documentation, OSHA enforcement records, Department of Homeland Security procurement databases, and IMO maritime safety protocols. Bottom-up triangulation across departmental budget allocations and top-down reconciliation against federal funding flows anchored volume estimates.
Segmentation dimensions modeled span service architecture, instructional modality, technology platform, and end-user category across the analysis window. CAGRs derived from scenario penetration curves weighted by regulatory mandate timing and hardware cost elasticity. Industry-specific forecast inputs incorporated NFPA 1403 live-fire restriction enforcement patterns and GPU price erosion trajectories from Taiwan semiconductor supply chain disclosures.
Underlying assumptions cover sustained federal grant earmark levels and Taiwan fabrication capacity stability, with deviation risk concentrated in EU MDR certification timeline extensions and instructor retirement acceleration. Revision becomes warranted when NFPA live-fire restriction scope crosses thresholds that eliminate remaining combustion-based training alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Human Resource Professional Services Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
GCC Soft Skills Training Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
Global Social and Emotional Learning (SEL) Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
US Life Coaching Market